The Truth Behind 5.2 Trillion in Cover: Agricultural Insurance Claims Settlement
Foodthink Speaks
Recently, frequent rainstorms and hail across the country have once again struck at the critical growth stages of many crops, leaving farmers facing enormous losses.
In public discourse, whenever the risks that climate change poses to agricultural production are discussed, experts, the public and even policymakers invariably turn to “agricultural insurance” as their lifeline. Yet the actual state of its implementation in our country, farmers’ attitudes towards it, and whether insurance truly means protection – these concrete questions have rarely been probed in depth.
In the latest episode of the podcast “Food Talk”, we interviewed Yi Fujin, Director of the Research Centre for Agricultural Risk Management and Safe Development at Zhejiang University. He explained in detail how farmers receive agricultural insurance payouts, and why some farmers cannot obtain compensation and do not trust agricultural insurance. More importantly, agricultural insurance itself faces growing pressure from rising claims. In an era of ever-shifting climate, how should this policy-based insurance develop?
Agricultural insurance is a highly complex topic that may be difficult to fully digest through a podcast alone. Foodthink has therefore prepared a curated text version of this episode’s highlights for readers to consult and reference.
How Much Has Agricultural Insurance Paid Out to Farmers?
Q
According to data from the Ministry of Finance, in 2025 the premium scale of agricultural insurance in China surpassed 155 billion yuan, providing more than 5.2 trillion yuan in risk protection to 125 million farming households. How should we interpret these figures?
Yi Fujin: The 155 billion represents total premium income – premiums paid by farmers plus premium subsidies provided by governments at all levels, bringing the total to 155 billion yuan. The 5.2 trillion in coverage is a theoretical ceiling: if every insured subject matter were damaged and all claims paid out at the maximum sum insured, the total would reach 5.2 trillion – 60% of the country’s agricultural GDP, which is already a remarkably high figure. But that 5.2 trillion is not liquid capital; it can only be paid out by drawing on premiums accumulated over many years, so it remains a rather abstract number. In practice, a payout of that magnitude all at once is virtually impossible. The figure that truly deserves attention is the 155 billion, which makes China’s agricultural insurance the largest in the world by premium volume. Approximately 80% of this 155 billion comes from government subsidies, with the remaining 20% paid in premiums by farmers.
Q
The farmers we spoke to had quite different experiences. Some received relatively satisfactory payouts, a few even regard agricultural insurance as a kind of savings product, while others simply cannot obtain compensation at all. What might be behind these disparities?
Yi Fujin: Our country’s agricultural production structure has one defining characteristic that cannot be overlooked: we are “a large country with small-scale farmers”. Smallholder farmers account for roughly 97% of all agricultural production entities in China. This fundamental reality means that agricultural insurance can never achieve 100% precision in implementation. Added to the inherent complexity of farming, it is very difficult for agricultural insurance to offer personalised, household-by-household, plot-by-plot services the way motor or property insurance can.
When we conducted fieldwork in Henan last year, we came across a particularly typical township with over 20,000 mu of arable land and more than 5,000 farming households. Insurance companies already have extremely thin staffing at the grassroots level. Generally speaking, one field officer at an insurance company is responsible for two to three townships of this size – and in some areas, even more. That means a single person may be covering 40,000 to 50,000 mu of farmland and tens of thousands of households. What makes this even harder is that agricultural production demands extremely tight turnaround times, and the government’s requirements for agricultural insurance are equally exacting: the entire process – from survey and loss assessment to the disbursement of claim payments to each household – must be completed within 14 days.
The problem, though, is that surveying, assessing and confirming losses across tens of thousands of mu, then disbursing payments, all within barely a fortnight is an immense burden. It is easy to imagine that in practice, faced with such a vast number of smallholder farmers, it is virtually impossible for insurers to go door to door and assess every single plot. This is the greatest obstacle to implementing agricultural insurance under the “large country, small farmers” reality.
As a result, some areas have adopted an alternative model in which a “collective policy” is signed at the village committee level. Once smallholder farmers in the village are hit by disaster, the insurance company randomly samples three to five plots within the village within 14 days, uses them to gauge the overall affected area and severity of damage across the entire village, and calculates the total payout based on the average level of loss. After the total amount is confirmed, village committee officials – who are, in effect, insurance liaison personnel employed by the insurer – then distribute the payout among households according to each family’s actual circumstances, completing claims settlement for every smallholder.
This gives rise to two types of scenario.
The first: although the current model is nominally called “yield insurance” or “full-cost insurance”, the principle actually applied in operation is area-yield insurance, which bases the settlement on the village’s average yield. For example, a particular farmer’s plot may sit on alluvial riverbank land and have been washed out by floodwater, yet the village as a whole may be unaffected. Under the random-sampling protocol, that plot may not be selected at all, or even if it is, it may have no meaningful impact on the village’s overall yield.
The second: after land reform, many farmers’ holdings are no longer a single contiguous parcel. A ten-mu plot may be split across four or five scattered patches, and in mountainous areas the fragmentation is even greater. Perhaps only one of those ten-mu plots has been damaged, and under the terms of the insurance contract this may not qualify as a reportable loss, triggering no payout whatsoever. But the farmer does not accept this, insisting that if any part of their land is damaged, they should be compensated regardless of the extent of the loss. Because farmers have limited understanding of the fundamental principles of agricultural insurance, compounded by insufficient explanation and outreach, there is a great deal of dissatisfaction among them.
So whether due to how the system is designed or the inherent nature of agricultural insurance itself, “wrong or missed claims” are a predictable outcome.
For large-scale operators, by contrast, holdings are generally 50 mu or more – in some regions, such as the Northeast, 100 or 300 mu. Every province essentially requires insurers to issue individual policies and sign separate contracts for these operators. After a disaster, insurance officers must visit each large farm specifically to carry out loss assessment. Relatively speaking, agricultural insurance is far more accurate for this group.
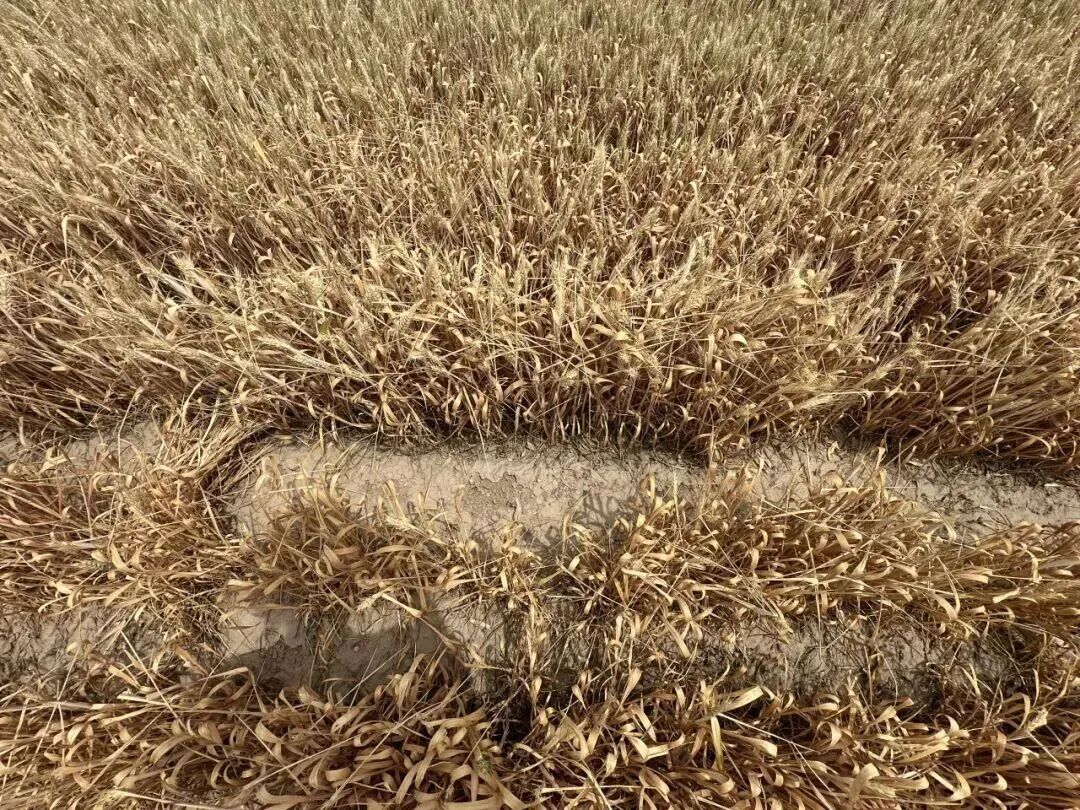
◉ In 2025, Shaanxi was struck by a severe drought. On alluvial riverbank land south of the Wei River, wheat turned yellow and parched – even the flag leaves had dried out; the soil at the base of the wheat plants was hot to the touch in daytime. Photo by Kong Lingyu.
Q
Under the principles of agricultural insurance, roughly how much compensation can a farmer expect, and how is the payout calculated?
Yi Fujin: There is another reason farmers feel payouts fall far short of their expectations: agricultural insurance – whether full-cost insurance or what is also called materialised-cost insurance – in practice only covers factor inputs.
Total production costs in agriculture are not committed all at once the way they are in industrial manufacturing; they accrue progressively. By the seedling stage, for example, roughly 50% of total costs may have been spent; by the jointing stage, about 70%; by the flowering stage, around 90%; and only when the crop reaches maturity and harvest are all costs fully incurred. The payout therefore depends on which growth stage the disaster strikes at.
Here is a straightforward example. Suppose the damage occurs during the wheat’s seedling stage – say, just after the New Year, a late-spring cold snap kills the young plants with frost. In that case, the insurance company will typically not pay the maximum coverage level but will calculate the payout based on the inputs already committed at the seedling stage. Measured against the total cost basis, the seedling stage accounts for only about 50%. So even if the insurance contract stipulates a coverage level of 1,000 yuan per mu, seedling frost damage may yield a maximum payout of only 50%, or 500 yuan per mu, because costs for the jointing, flowering and later stages have not yet been incurred. If, however, the disaster occurs at the harvest stage – for instance, if lodging or prolonged heavy rain results in total crop failure – the payout may reach the full 100%. Agricultural insurance contains many technical details that are not sufficiently spelled out in the policy terms, yet in practice, claims are settled exactly as described above.
Q
Then why do some farmers regard agricultural insurance as a kind of savings product?
Yi Fujin: The industry calls this practice a “premium rebate”. In years when farmers suffer no losses, the insurer returns part of the premium to maintain their willingness to renew cover the following year; if a disaster does occur, claims are still processed through the normal procedure.
How should we understand the premium-rebate issue, and what lies behind it? Because payouts to the vast number of smallholder farmers are based on sampling for loss assessment, they are inherently imprecise, and the premiums are set too high – one could even say the insurance product is “substandard”. To keep farmers motivated to maintain cover, insurers must give farmers some return for an agricultural insurance product that does not, in truth, deliver value for the price. So in practice, in years without disaster, insurers return part of the premium to farmers.
This is certainly not good for agricultural insurance, whose ultimate aim is to build up an insurance capital surplus in years without disaster so that funds are available to pay out when real catastrophe strikes. What the current practice does is spend down money that should be retained as surplus on minor incidents, leaving nothing for genuine disaster – creating the so-called “small disasters get big payouts, big disasters get small payouts” problem. That is why the 2024 National No. 1 Document called for “dual precision” – precision insurance enrolment and precision claims settlement. This has become the most pressing real-world challenge in agricultural insurance today.
◉ Rice paddies submerged by floodwater suffered widespread lodging, with muddy water still clinging to the grain heads and stalks. Photo by Yvonne.
Facing Widespread Crop Damage –
Can Insurance Companies Afford to Pay?
Q
So if a large-scale disaster strikes – as happened in North China last year – can local insurers actually afford to pay? If a particular area is hit, is it the local branch that covers the claims, or would the provincial company or the national headquarters also step in to pay?
Yi Fujin: Insurers themselves vary enormously. In Henan, the largest company is Zhongyuan Agricultural Insurance, which has its own sub-branches at the grassroots level, called county-level sub-branches. For minor disasters, as long as the payout is not too large, it can be covered through the county-level or prefecture-level sub-branch. But for a very major disaster – especially one of the scale we saw last year, with widespread crop loss – neither a single county branch, nor even a prefecture-level sub-branch, nor the provincial company can possibly afford to pay.
Because the premium collected is only 40 yuan per mu, while that 40 yuan must cover a payout of 200 yuan should a farmer suffer a loss in any given year. In other words, the premiums collected are not enough to sustain a 200-yuan payout. In such cases, the company must rely on its accumulated risk reserves – the risk surplus – to fund disaster payouts.
In a normal year, insurers typically set aside a “catastrophe reserve” from the premiums they collect. They also purchase agricultural reinsurance from reinsurers. If a local branch cannot meet its payout obligations, claims can be settled from the catastrophe risk reserve, or the risk can be transferred through a reinsurer. But a major challenge now is that China has not yet established a fully developed catastrophe risk-response system.
Ideally, with a company like PICC, if a regional branch’s claims exceed its capacity, headquarters can theoretically mobilise resources across all regions to coordinate the response. But a regional agricultural insurer such as Zhongyuan Agricultural Insurance in Henan or Guoyuan Agricultural Insurance in Anhui is in a far weaker position. If a major disaster strikes the area, the payout burden becomes extremely heavy, and it is very difficult to spread risk on a national scale. This can lead to something akin to a bank run – the company simply cannot pay out so much at once and may face enormous financial pressure.
In the United States, Canada, Japan and even India, the central government typically establishes an emergency fund, since national budgets already contain contingency reserves that can be drawn upon, and the shock of catastrophe risk can also be absorbed through the issuance of public bonds. In China, however, the institutional mechanism in this area remains relatively underdeveloped. In 2020, the China Agricultural Reinsurance Company was established at the national level. At present, the arrangement still operates through a 20% cession – for instance, if an insurer collects 1 billion yuan in premiums in a single province, it must cede 20% of that, or 200 million yuan in premiums together with the corresponding risk, to the reinsurer – thereby forming a risk-sharing mechanism between China Agricultural Reinsurance Company and local insurers.
But this does not solve the problem at root. The risk of exceeding payout capacity is widespread – when catastrophe risk strikes on a national scale across provinces such as Henan, Anhui, Shanxi and Shandong, a cession mechanism is certainly not enough. Under such circumstances, the operations of any commercial insurer become unsustainable. And in China, the development of the institutional framework in this area still lags considerably behind.
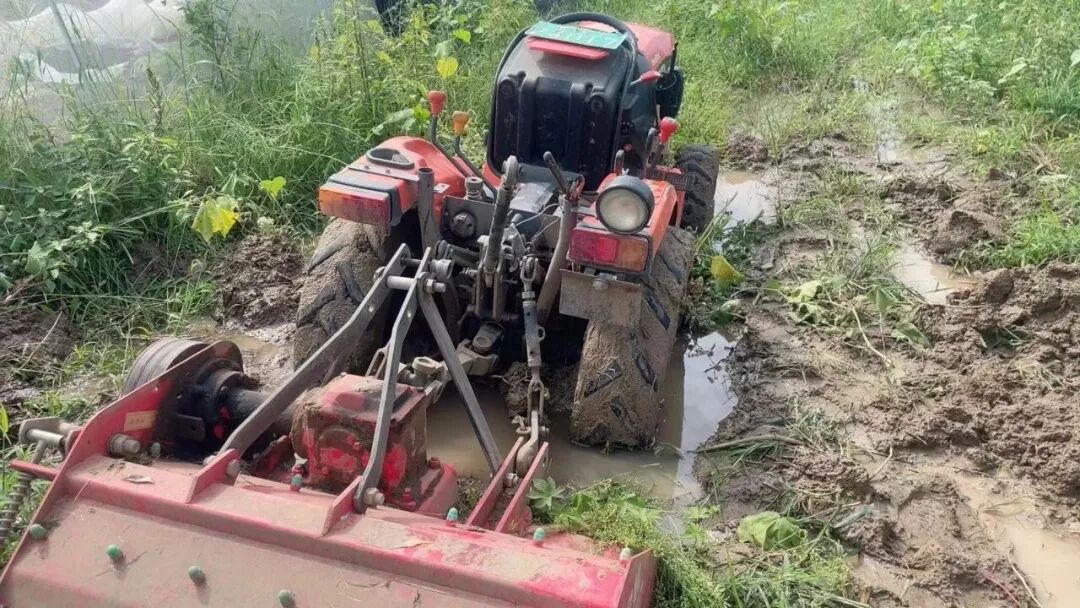
◉ After the rain, a tractor is bogged down in the mud, unable to move. Heavy machinery operating on farmland after rain also compacts the soil, damaging arable land. Image source: Xiaoliushu Farm
Climate Change Intensifies Claims Pressure
Q
You mentioned earlier that the net profit margin in agricultural insurance once reached 10%. That sounds quite profitable.
Yi Fujin: It sounds profitable, and indeed it has been. Because the overall risk associated with our bulk agricultural commodities – staple grain crops, that is – is relatively manageable. Although natural disasters have been worsening year after year, the level of food security has continued to improve, with successive years of higher output and bumper harvests. This means that, in broad terms, disasters in agricultural and food production remain controllable for farmers. On this basis, combined with the practice of collective enrolment and collective claims settlement for smallholder farmers, insurers save enormously on operational costs. As a result, for quite a long stretch of time, the average profit margin on agricultural insurance business hovered at around 9%.
The issue is not that the profit margin is too high, nor that insurers should not earn this money; it is what the money actually represents. On the balance sheet, of course, it registers as profit. But if you account for the enormous year-to-year variation in both the frequency and severity of agricultural disasters, the picture changes. Take the United States, where agricultural insurance is the most developed and was the earliest established: in extreme years, the loss ratio can reach 160%, 170%, or even 200%. That is unimaginable in motor insurance, but in agricultural insurance it happens. When a truly massive disaster strikes – as in 2022, when regions south of the Yangtze received virtually no rainfall for more than half the year – if claims were paid out strictly according to actual losses, the loss ratio would not fall below 200%. That is perfectly normal.
So the surplus that many insurers carry on their books can just as reasonably be described as profit as it can be described as a risk reserve set aside to meet future catastrophe risk.
But at present, the catastrophe risk protection system has yet to be established, and government policymaking in this area remains very slow. Moreover, a large part of this surplus actually stems from insurers benefiting from their cooperation with the government: through this partnership, the government absorbs the cost, while the profit accrues to the insurers. Once this surplus is registered as book profit for insurers, it should in future be pooled at the national and provincial levels in the form of a catastrophe risk reserve or a dedicated management fund. Insurers’ accounting practices will also need to undergo a corresponding adjustment in the years ahead.
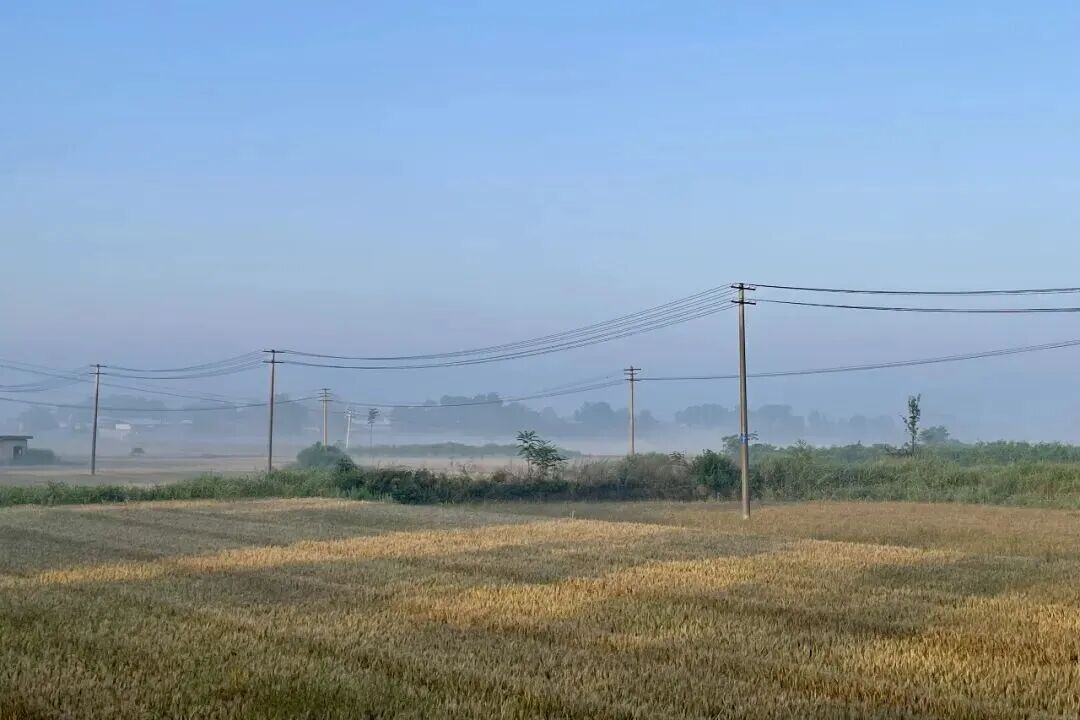
◉ In 2023, the Guanzhong region of Shaanxi endured ten consecutive days of harvest-ruining rain, leaving patches of the wheat crop mouldy. Image source: Lüwo Farm
Q
You have also mentioned before that insurers’ profitability has declined in recent years. I recall you saying the profit rate is now around 3–5%. What is driving that?
Yi Fujin: The profit margin may not be quite that low, but it is still on the high side overall. In any case, the decline has been driven by a confluence of factors.
First, as the climate changes and extreme weather events become more frequent, the claims pressure on insurers is genuinely and steadily increasing.
Second, the government itself has recognised that insurers’ average profit margins are indeed very high. Because these funds are public money – local governments are spending real cash on premium subsidies – in areas where the understanding of insurance remains shallow, local authorities demand that, for example, if the treasury allocates 50 million yuan, at least that much must be spent by year-end. For local governments this is advantageous, because the money yields visible results within the same year, going out as payouts to farmers. But when a genuine catastrophe hits, the problems emerge.
Third, farmers’ awareness of their rights is growing, which places considerable pressure on insurers’ regulatory compliance. Of course, moral hazard is also present in this. During our fieldwork in Henan and Anhui last year, we encountered exactly this issue: some farmers felt that a payout of 80 or 90 yuan was simply not enough and demanded at least 500 or 600 yuan, since the coverage ceiling was 1,000 yuan. But given the insurer’s payout capacity, meeting such demands was simply impossible.
Fourth, under increasingly stringent regulation in recent years, insurers have been making payouts as generously as they can.
These four factors together have brought about the declining profit margins we now observe. Is this decline a good thing or a bad thing? From my own perspective, I am not convinced it is necessarily good. Because the catastrophe risk management fund has still not been set up, the moment a major disaster strikes, insurers’ payout capacity will be severely compromised. So a falling profit margin is welcome news from the farmers’ point of view, but at the same time it is a warning sign.
Q
What is the actual state of our risk fund pool at present – how much money can it actually deploy? Do you have any insight?
Yi Fujin: I do not have the full picture on that figure, but from what I have gathered indirectly, it is not particularly high and may in fact have declined somewhat. In some countries – Japan, for instance – accumulated risk funds have reached 1.6 times premium income, earmarked for coping with extreme disasters. Our country is nowhere near that level.
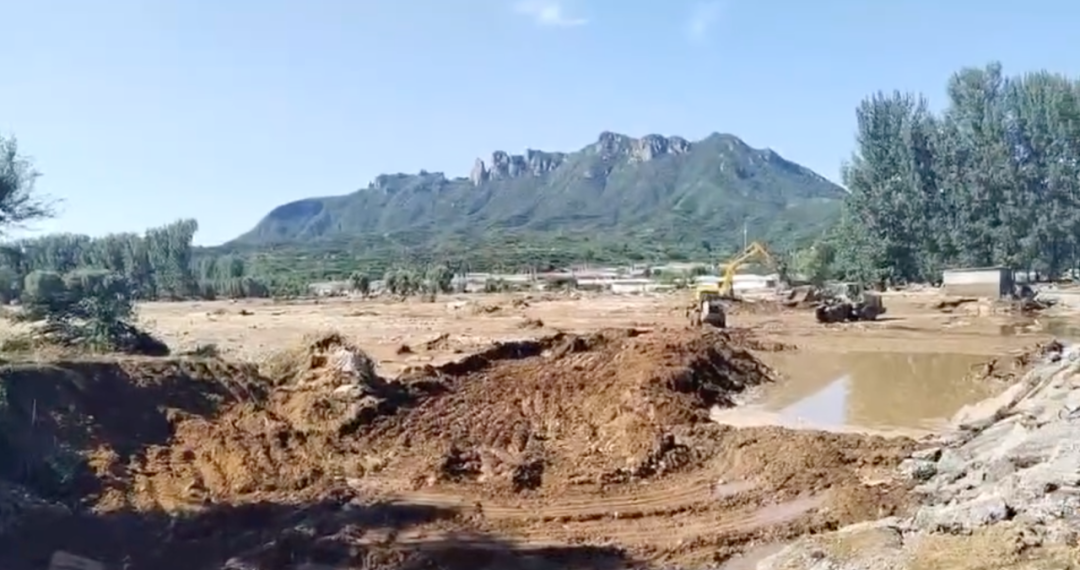
◉ In July 2025, an exceptional rainstorm struck Beijing once again. Sohu Farm, beside the Qingshui River in Beizhuang Town, Miyun District, saw all 450 mu of its land swallowed by floodwater. The flood nearly erased every trace of the farm – all that remained were collapsed road embankments, waterlogged mud, and a scattering of construction debris. Photo by Zhen Rui.
Q
Roughly 80% of the funding for agricultural insurance comes from fiscal subsidies. We had a phase of purely market-based agricultural insurance operation in the past, but it failed, and it was only later that policy-based insurance took its place. Looking at things as they stand now, is there any prospect of agricultural insurance weaning itself off fiscal subsidies?
Yi Fujin: Indeed, from 1982 right through to 2004, the entire system operated on a commercial footing. The logic of a wholly market-based model failed – and that is not a uniquely Chinese case; no government anywhere in the world has managed to run agricultural insurance on a purely commercial basis. A key reason is that agricultural risk is simply too high. On the supply side, the cost of delivering agricultural insurance is also far too high. On occasion, I half-joke that although agricultural insurance is run by commercial entities, its territorial coverage rivals that of the state itself, with a dedicated insurance representative stationed in virtually every township – a presence that demands staffing, transport, and various technical means, all adding up to a very high cost. These costs alone mean agricultural insurance is not a profitable business. All in all, marketising agricultural insurance – taking it outside the reach of government support, whether fiscal or administrative – has no successful precedent anywhere in the world. It is simply not feasible in practice.
Q
While I was in Henan, I met some farmers who clearly doubted the insurers’ ability to pay. What concerned them, though, was the poor state of local finances – they felt the local government was stretched so thin it could not possibly protect them. So does local finance play a role in the payout process?
Yi Fujin: There is certainly an element of speculation in what farmers assume. The current weakness of local finances does prevent insurance from fulfilling its proper risk-protection role, but the root cause lies in the distinctive logic of our fiscal subsidy system.
Under our present subsidy structure, insurers first collect 20% of the premium from the farmer. The county-level government then matches with a further 5% to 10%. Only once that matching contribution is in place can the application move up to the prefecture-level city for fiscal subsidy, then on to the provincial level, and finally to the central Ministry of Finance – and the central government will only release its subsidy once contributions from all three lower tiers have been confirmed. This gives rise to the problem of premium receivables. In the central and western regions in particular, local finances are tight and local governments simply cannot find the money. So right at the enrolment end of the chain, even though the farmer may have already paid their share, if the local government cannot come up with its contribution, the entire insurance chain breaks – the policy was never properly concluded in the first place. This is an enormous problem at present. With local finances stretched so thin, if the contract-signing process has not even been completed, how can one talk about payouts?
We recently saw a figure indicating that the central government has earmarked roughly 50 to 60 billion yuan in budgetary funding. But in practice, from 2024 onwards, the completion rate of central fiscal subsidies has already fallen below 100%. The most important reason is that local governments cannot come up with their share at the source – they cannot help farmers pay their premiums – so the central money cannot reach the end of the chain either. This is an extremely acute problem right now.
That said, from the point of view of insurance delivery, local governments remain indispensable. Without the endorsement of township governments or village-level collective organisations, smallholder farmers simply cannot participate in agricultural insurance schemes.
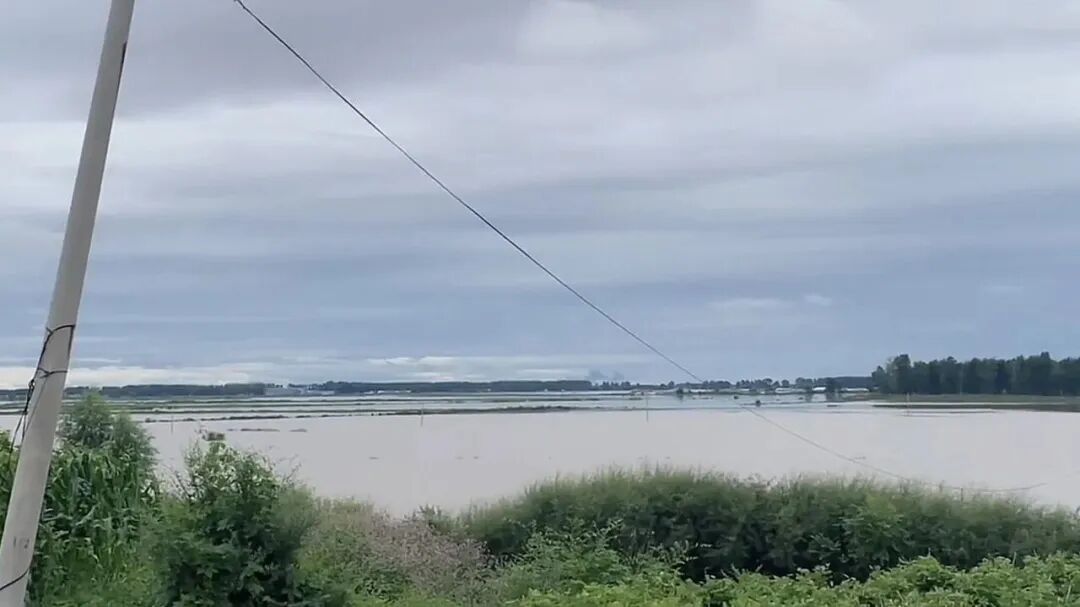
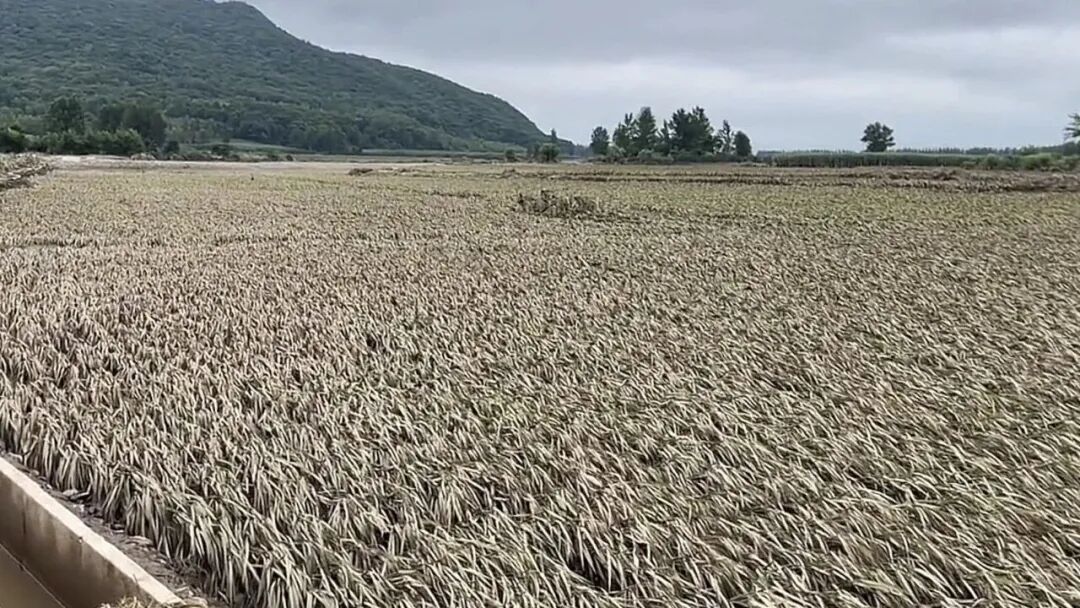
◉ In early August 2023, Wuchang in Heilongjiang was hit by a rare combination of torrential rain and flooding. Around 40% of the area’s 2.5 million mu of farmland was submerged. The zone shown in the image was once a stretch of paddy fields, now entirely drowned beneath the floodwater. Photo by Yvonne.
Agricultural Insurance: The Risk Consideration Paid for Food Security
Q
I recently came across an argument that agricultural insurance is essentially a pay-after-the-damage model, and that the way forward should be to reduce the incidence of disasters – that prevention and mitigation matter more than payouts. But is it actually possible for agricultural insurance to shift from a post-event safety net to pre-event disaster prevention?
Yi Fujin: In the case of minor floods or episodes of concentrated rainfall, insurers can certainly help by providing farmers with pumps, drought-resistant varieties, and the like. But once an extreme disaster strikes, such measures are simply no use at all.
So from a logical standpoint, I do not object to the general idea – ex-ante prevention is important and does work for certain types of disaster. But when it comes to more severe events, preventive measures have very little practical effect.
The most fundamental question is: what exactly is the role of agricultural insurance?
If agricultural insurance is positioned as a preventive instrument, then our current financial regulations do not allow it. In conversations with colleagues in the industry, I have learned that 20% of premium income is designated as management costs, and only a portion of that 20% may be drawn upon for preventive work – the remaining 80% of premiums cannot be diverted for prevention.
In any case, if agricultural insurance is expected to substitute for far more effective measures – farmland water-conservancy infrastructure, improvements in production technology, high-standard farmland – then priorities are plainly inverted. The division of labour and the positioning of agricultural insurance within China’s overall agricultural policy framework are therefore critical.
I have heard many different views, and the overwhelming majority of scholars, government officials, and insurance-industry professionals share the view that the government’s premium subsidy for agricultural insurance is essentially support for agriculture, or for farmers in managing risk. On conventional logic, that is indeed the case.
But there is another dimension. When we look at agriculture – particularly grain production – from a higher vantage point, the adequate supply of grain, that is, food security, is the cornerstone of social stability and development; it is a public good. Everyone stands to benefit from food security. In a normal year of good harvests, consumers can buy ample grain on the open market and enjoy the dividends of food security. But when output falls, the state intervenes through macroeconomic regulation, releases grain from state reserves to stabilise prices, and adjusts domestic supply through imports. Consumers suffer relatively little loss, yet farmers – by virtue of the national food-security strategy – bear the damage, and no one pays them a corresponding premium, or even a partial compensation.
In other words, in the course of achieving the strategic objective of food security, society as a whole reaps the benefits of abundant grain supply, yet we do not pay the corresponding risk consideration for the risk of reduced grain output.
So from this perspective, the government’s premium subsidy for agricultural insurance is not a subsidy at all – it is the risk consideration the government should be paying in order to deliver food security.
Looking across more than a thousand years of Chinese history, the old adage “cheap grain harms the farmer” – when a bumper harvest drives prices down, farmers gain nothing; and yet when output falls, state intervention to control grain prices still leaves farmers at a loss. Set these two realities side by side, and farmers bear every loss while society shares the market’s gains – an imbalance in which risk and reward are wholly mismatched. The government therefore has a duty to take measures that help farmers manage risk, so that low reward is matched with low risk. From both a risk-management standpoint and one of social equity, it is absolutely right that the government should pay this sum.
– This is Foodthink’s 817th original article –
Foodthink
Guest
Yi Fujin
Qiushi Distinguished Professor at Zhejiang University and Director of the Zhejiang University Centre for Agricultural Risk Management and Safe Development, with long-standing research focus on agricultural risk management and agricultural insurance policy.
Interview and transcription: Xiaodan
Editing: Yuyang, Tianle
Layout: Xiaoshu
Scan to tip and support original Foodthink content
▼
▼
Click the image to read related articles
▼
Click a keyword to view more article collections
Seeds | Farming Technology | Policy | Fermentation | Nutrition | Fruit | Fisheries | Events | Recruitment | Takeaway | Wet Markets | Animal Husbandry | Food Talk | Sharing Sessions | Reading Groups | Harvest Celebrations | Smallholder Stories | Climate Change | Rural Development | Cooperative Economy | Urban Farmers | Food Safety | Digital Technology | Biodiversity | Pandemics & Food | False Solutions | Lianhe Creative Programme | Agroecology Internship Programme
Beijing|Hebei|Shanghai|Guangdong|Guangxi|Henan|Sichuan|Jiangxi|Xinjiang|Shaanxi|Hong Kong|Chongqing|Zhejiang|Jiangsu|Guizhou|Northeast China|Taiwan|Inner Mongolia|The Philippines|Canada|Russia|Mexico|Italy|The United States|The UK|Germany|The Netherlands|Thailand|Sweden|Japan